Canada’s financial system needs overhaul to close funding gaps for SMEs and stem the loss of talent and businesses

Fundamental changes are required to the Canadian financial system to fix persistent funding gaps for SMEs and stem the loss of Canadian talent, business and intellectual property ownership, according to a new report by a Senate committee.
 Numerous changes are needed, including creating an “SME Office” focused on ensuring capital and credit for SMEs, that’s accountable to a single minister and responsible for accelerating overall business innovation and growth in Canada, the Standing Senate Committee on Banking, Commerce and the Economy says.
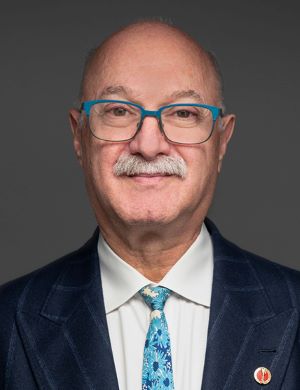
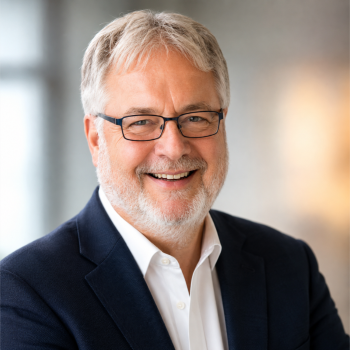
To fix Canada’s declining productivity, “We’ve got to get businesses humming, and the way to get them humming is to make sure that they're able to scale up and we don't have to sell them to foreigners,” Senator Daryl Fridhandler (photo at right), who was a member of the committee that produced the report, said in an interview with Research Money.
If the federal government doesn’t act to ensure sufficient investment capital flows to SMEs, “the productivity will continue to decline” and Canada will lose its innovative scaling companies, he warned. “They’ll go build elsewhere.”
Fridhandler said Ottawa should in this fall’s federal budget create the SME Office with a minister solely responsible for SMEs and federal programs for them.
“They're such a hugely important part of our economy, and there's no reason that they shouldn't get that kind of attention,” he said.
There is sufficient capital in Canada, and “somehow we've got to get it loosened up to allow these businesses that want to scale up to scale up,” he added. “I think if we've got someone who sits at the cabinet table and counts for the SMEs, that’s a good first step.”
Another committee recommendation that Ottawa could act on in the upcoming budget is to expand the flow-through shares tax credit for Canadian investors in sectors other than mining and oil and gas, Frindhandler said.
The Liberals mentioned doing this in their 2025 election platform, but it has yet to be done.
The Carney government also could also allow Canadian investors and entrepreneurs to defer paying capital gains taxes when the proceeds from a domestic business transaction are rolled over or reinvested into another homegrown venture, he said.
Throughout its study, the committee said it heard consistent testimony that Canada does not face a shortage of capital, but rather a fundamental challenge in accessibility, the allocation and deployment of capital across the SME lifecycle.
Witnesses emphasized that Canada performs relatively well in supporting business startups but faces persistent challenges in supporting firms to scale domestically, particularly in accessing growth-stage and late-stage financing for SMEs.
“Structural barriers in Canada’s financial system are preventing small and medium-sized enterprises from reaching their full potential,” said Senator Clément Gignac, chair of the committee.
“These businesses are the backbone of our economy. We must make fundamental changes to help them succeed and keep their innovations in Canada,” he said.
Canadian financial markets do not offer SMEs competitive, affordable and timely access to capital and credit, the committee said in its report, From Potential to Prosperity: The urgent case for greater investment in Canada’s SMEs.
“The Committee is deeply concerned that Canada’s largest institutional investors (financial conglomerates, insurers, pension funds) and pools of capital appear disinclined to finance the growth of Canadian SMEs, thus limiting our country’s ability to capitalize on Canadian talent, our investments in research and development and, ultimately, our ability to retain and grow our most promising innovative businesses.”
As of December 2024, SMEs accounted for 99.7 percent of employer businesses in Canada, and in 2022, SMEs accounted for nearly half of the gross domestic product generated by the private sector.
“They are the primary source of private-sector employment, the foundation of local economies and a key driver of innovation and growth. Their success is critical to Canada’s long-term prosperity, productivity and competitiveness,” the committee’s report said.
Although Canada is home to a vast number of SMEs, the country’s financial sector is dominated by a handful of large financial conglomerates, “creating a persistent and increasing disconnect between those seeking credit and capital, and those controlling its allocation,” according to the report.
Designed primarily to promote stability and efficiency at scale, the financial system tends to favour larger, lower-risk, asset-backed transactions. As a result, many promising economic opportunities for SME expansion, innovation and succession are rendered inaccessible due to structural barriers within Canada’s financial sector, the report said.
“Canada’s SMEs are underbanked and overcharged,” according to the report. In Canada in 2021, 11.6 percent of outstanding loans were made to SMEs, compared to the 44-percent average among countries in the Organization for Economic Co-operation and Development (OECD).
In 2022, the average SME interest rate was 6.2 percent in Canada, whereas the OECD median is 4.4 percent.
Evidence presented to the committee highlighted a disconnect between the perspectives of financial institutions, which reported strong availability of credit, and SMEs, which frequently experience barriers to accessing financing, particularly in the absence of tangible collateral or sufficiently established cash flow.
“The committee surmises that many SMEs are turned away at the door, so loan application fulfillment is not a true reflection of SME approaches to banks.”
Large pools of domestic capital are under-deployed in supporting Canadian SMEs
The committee also observed that large pools of domestic capital, including pension funds and other institutional investors, are under-deployed in supporting Canadian SMEs, with a significant proportion of investment directed toward foreign markets.
The “Maple Eight” public sector pension funds managed $2.3 trillion in assets at the end of 2024, with domestic investments amounting to less than half of the industry’s global average.
The committee said it is deeply concerned that existing financial institutions continue to direct a disproportionate share of capital toward low-risk assets, particularly real estate, while innovative and growth-oriented SMEs, particularly those based substantially on intangible assets, face persistent financing gaps.
The federal government has the legislative authority to, for example, to modify the investment rules for federally regulated funds, like the Canada Pension Plan Investment Board, to require that the pension fund invest a certain percentage of its assets in Canadian SMEs. Pension funds have strenuously objected to such a move.
Ottawa also could take a “carrot” approach and offer pension funds that co-invest in SMEs tax credits, Fridhandler said.
The government also could use its “moral suasion” to say, “It’s time you guys did a little bit more for the betterment of the country,” he said.
Similarly, he added, Canada’s Big Banks should be persuaded to reduce their huge risk-aversion and be more flexible on capital requirements so they can provide more loans to SMEs. “You could take the foot off the pedal bit, and encourage lending.”
Businesses in Canada need to be able to excel, rapidly scale, grow and draw in global talent and investment. Yet business investment in Canada has dropped from 14 percent of GDP in 2014, to 11 percent in 2024, the committee noted.
Increasing globalization and the growing role of foreign investment have provided Canadian firms with access to capital from foreign jurisdictions.
However, this has also contributed to the premature sale of promising companies and the transfer of ownership, investments in research and development, intellectual property and future economic value outside of Canada, the report noted.
Canada currently lacks both a coherent strategy and a centralized leadership and organization to lead the way in addressing the structural problems within Canada’s financial system that create barriers or could enhance opportunities for many SMEs in accessing capital, the committee said.
While numerous programs and institutions exist to support SMEs, the evidence suggests that policy decisions are too often uncoordinated and disconnected from the reality faced by entrepreneurs and growing businesses.
”Canada needs a more coherent structure to convert innovation, through to scale up, to Canadian domiciled enterprises that grow to global leaders and contribute to the nation’s overall productivity.”
“The government spends $7.5 billion per year on research, $4.2 billion to the granting councils and $3.3 billion internally with absolutely no strategy whatsoever to generate and corral that research money into intellectual property that has positive spillover for Canadian companies,” Jim Balsillie, chair of the Council of Canadian Innovators, told the committee in testimony.
The committee also pointed out that federal procurement should play an important role in supporting Canadian SMEs.
Witnesses emphasized that government procurement should be considered a strategic economic development instrument, capable of helping Canadian firms scale, attract investment and retain ownership domestically.
The committee said it is troubled that innovation programs fail to ensure that IP developed as a result of federal grants or programs stays in Canada over the long-term, and that foreign companies often acquire these valuable assets and reap the economic benefits of taxpayer funds. Witnesses highlighted that publicly funded research institutions frequently partner with foreign corporations without adequately protecting Canadian ownership of resulting IP.
Committee makes numerous recommendations:
To tackle the structural deficiencies that have manifested themselves over time in Canada’s financial system and boost access to capital for SMEs, the committee called on the federal government, directly or indirectly, to: (See the report for the fully detailed recommendations).
- create an SME Office, accountable to a single minister, responsible for accelerating overall business innovation and growth in Canada. Align the policies, services and programs in ways that catalyze investment from the private sector domain and investment experts, and publicly report impact date by program.
- launch a comprehensive national strategy to improve the flow of capital to SMEs, integrating policies suggested throughout this report in relation to access to credit and capital, intellectual property, data and regional development.
- enhance tax competitiveness for both SMEs and investors in SME growth through accelerated changes to tax policy.
- enable and encourage regulatory changes that will expand SME access to capital and credit by creating robustly competitive financial markets and better enabling new entrants in those markets to competitively access the capital they require to increase their investment and/or lending to SMEs.
- encourage the provinces to introduce robust market reforms that will enable Canada’s public and exempt investment markets to once again become globally competitive and a viable alternative for growing Canadian SMEs to create liquidity and raise capital.
- take action to support the Canadian acquisition and ownership of intellectual property and its retention in, and commercialization from, Canada as recommended in the Standing Senate Committee on Banking, Commerce and the Economy’s June 2023 report, Needed: An Innovation Strategy for the Data-Driven Economy.
- ensure that Canadian SMEs can reliably compete for timely access to federal procurement opportunities that reward excellence and innovation. The revenue from those projects will increase SME access to both credit and capital.
- encourage entrepreneurship across our country by recognizing and addressing barriers that demonstrably limit access to credit and capital of entrepreneurs from underrepresented groups and communities.
- apply stronger conditions on government grants to encourage companies receiving public funding to stay and grow in Canada, such as a variable rate of claw back or repayment mechanism on funded intellectual property should a company sell or move that intellectual property offshore.
- introduce or expand measures allowing for full and immediate expensing of capital expenditures related to modernization, digital adoption, artificial intelligence, machinery and innovation processes in order to accelerate productivity growth of SMEs.
- examine policy and regulatory options to increase lending to SMEs by federally regulated financial institutions (banks, insurers and credit unions), including a review of “capital intensity” requirements to ensure they appropriately support SME lending, in particular to intangible asset-based SMEs, while maintaining financial stability.
- enhance competition and access to innovative financial services companies in ways that will pressure Canada’s financial conglomerates to improve their services and offerings available to SMEs, while also requiring them to limit the costs for SMEs to switch to another financial institution.
- consider policy, regulatory and legislative initiatives to encourage pension funds and other large pools to deploy more significant amounts of their capital into SMEs – either – directly or through co-investment – with venture capital or private debt institutions.
Testimony to the committee: a sample
“We just had the government announce some very good measures for the Scientific Research and Experimental Development tax credit, or SR&ED,” said John Ruffolo, founder and managing partner Maverix Private Equity.
“Why do we give this credit to foreign-based companies whose intellectual property is not owned in Canada? We don’t benefit from it. It is an old reference to job creation. We are one of the only countries in the world that award [research and development] tax credits to foreign-based companies who don’t have their IP here,” Ruffolo said.
“Figuring out how to recapitalize the country right now is mission critical. It is how we will build wealth, prosperity and sovereignty, ultimately. There is no silver bullet for this,”said Benjamin Bergen, CEO of Canadian Venture Capital & Private Equity Association.
“Canada must treat the capital life cycle as a connected system. Early-stage investment, growth capital and the liquidity that comes from institutional investors are sequential stages, not separate ones. A weakness at any one stage compounds across the others,” said Claudio Rojas, CEO of the National Angel Capital Organization.
“Canada needs to treat capital deployment as a core component of industrial policy. Specifically, pension funds and chartered banks, institutions that benefit from public policy and taxpayer support, should play a more active role in financing Canadian scale-ups,” said Hamid Arabzadeh, chairman and CEO of Ranovus.
“Our analysis revealed that around 350,000 entrepreneurs lack the financing they need to realize their projects and achieve their ambitions. Most of these entrepreneurs are from groups under-represented in the portfolios of major financial institutions: businesses in rural and remote regions, women entrepreneurs, Black entrepreneurs, newcomers, and Indigenous entrepreneurs,” said Isabelle Hudon, president of the Business Development Bank of Canada
“If Canada wants the most innovative companies to scale domestically, we must provide a compelling reason for them to stay. Rebuilding resilient capital markets in the ecosystem is not only a financial priority, but it’s also a national economic imperative,” said Dan Daviau, chairman of Canaccord Genuity Group Inc.
Senator Danièle Henkel, a member of the Senate committee that produced the report, said: “Having experienced the realities of entrepreneurship firsthand, I know how much access to financing can make a difference.”
“We ask a great deal of our entrepreneurs: to innovate, take risks, export and create jobs. We must also ask ourselves whether our financial system is truly giving them the means to succeed, including women and entrepreneurs from diverse backgrounds,” Henkel said.
“Time is of the essence,” the committee warned. “Canada’s innovators and entrepreneurs represent the future of our economy. Competitive access to credit and capital is critical to enabling our SMEs to compete globally, both in and from Canada.”
R$
Events For Leaders in
Science, Tech, Innovation, and Policy
Discuss and learn from those in the know at our virtual and in-person events.
See Upcoming Events
You have 0 free articles remaining.
Don't miss out - start your free trial today.
Start your FREE trial Already a member? Log in
By using this website, you agree to our use of cookies. We use cookies to provide you with a great experience and to help our website run effectively in accordance with our Privacy Policy and Terms of Service.